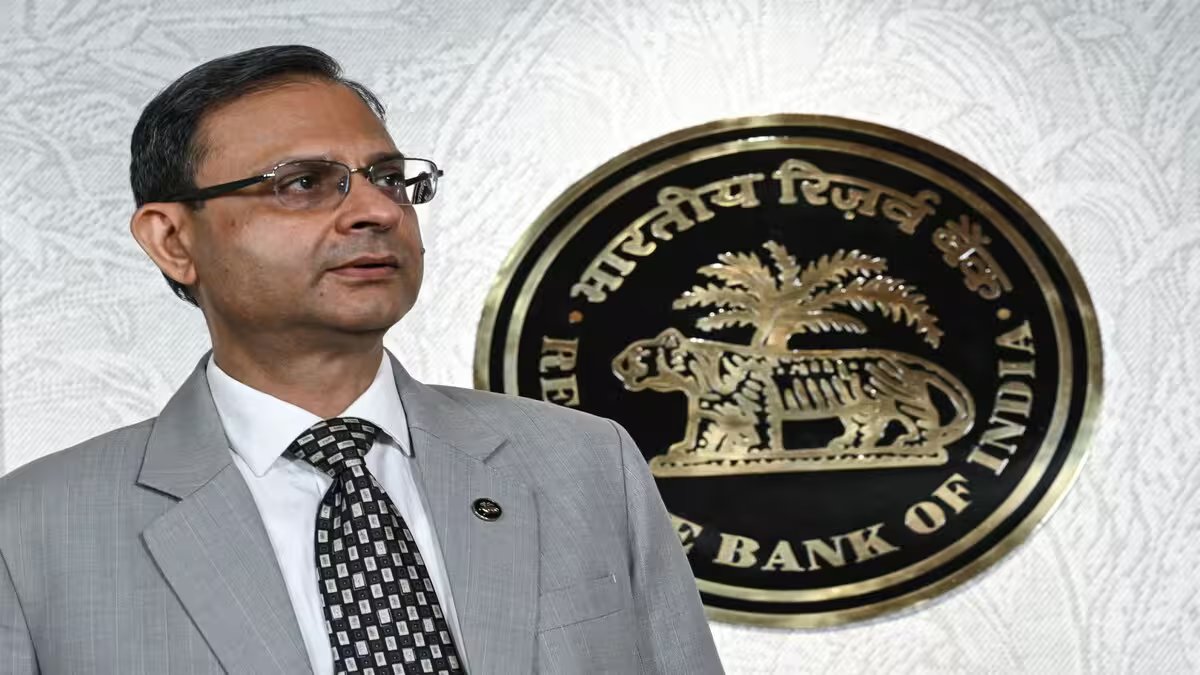
The RBI has raised borrowing costs for the first time since February 2023, signalling a shift in its policy calculus as inflation pressures broaden and global monetary conditions turn tighter.
The Reserve Bank of India has raised its benchmark repo rate by 25 basis points to 5.50 per cent, marking its first rate hike since February 2023 as the central bank steps up its response to renewed inflationary pressures.
The decision marks a sharp turn for monetary policy after a prolonged period of easing and then holding rates steady. The RBI had cut the repo rate by a cumulative 125 basis points during 2025 before keeping it unchanged at 5.25 per cent through its recent policy meetings.
The rate hike had been largely anticipated by financial markets. A Reuters poll showed a majority of economists expecting a 25-basis-point increase, while interest-rate markets had already priced in much of the move.
But the significance of the October decision goes beyond the quarter-point increase.
“The MPC delivered a 25 bp rate hike in line with expectations, with a surprise shift in stance towards recalibrated tightening. We continue to see 25-50 bp of additional rate hikes going ahead, with further upside if global risks persist,” Upasna Bhardwaj, Chief Economist, Kotak Mahindra Bank said.
For the RBI, the challenge is no longer simply about containing food-price volatility. Inflation has broadened at a time when crude oil prices have surged amid geopolitical tensions, the rupee has remained under pressure and global bond yields have moved higher.
 More from Business
India’s consumer inflation rose to 4.82 per cent in August, remaining above the RBI’s 4 per cent target for the third consecutive month. At the same time, the domestic economy has retained considerable resilience, giving the central bank greater room to prioritise price stability without having to respond to an outright growth shock.
“The RBI’s 25 bps repo rate hike to 5.50% is broadly in line with our expectations, given the challenges posed by weak monsoons, the potential impact of El Niño, heightened geopolitical conditions and global trade and inflationary pressures. The shift to a ‘calibrated tightening’ stance signals that further rate action will remain data dependen,” Shishir Baijal, International Partner, Chairman and Managing Director, Knight Frank India said.
The RBI’s next challenge will therefore be to prevent a temporary inflation shock from becoming entrenched in expectations.
The focus now shifts to the future rate path. Markets will closely parse the MPC’s guidance on whether the October hike is a one-off insurance move or the beginning of a broader tightening cycle. Some economists have already argued that the repo rate could rise further, potentially towards 5.75-6 per cent if inflation remains elevated.
Liquidity management will be another critical piece of the policy puzzle. The banking system continues to carry substantial liquidity, while the RBI has been using tools including variable-rate reverse repos, bond operations and foreign-exchange swaps to influence financial conditions.
For borrowers, the immediate implication is straightforward: the cost of money is moving higher. Banks and lenders could eventually transmit the increase into lending rates, raising borrowing costs for home loans, corporate credit and other floating-rate loans.
For savers, however, higher rates could gradually translate into better returns on deposits and other fixed-income instruments.
The larger message from Mint Road is clear: after years of prioritising growth support, the RBI is once again putting inflation containment firmly at the centre of its monetary-policy calculus.